
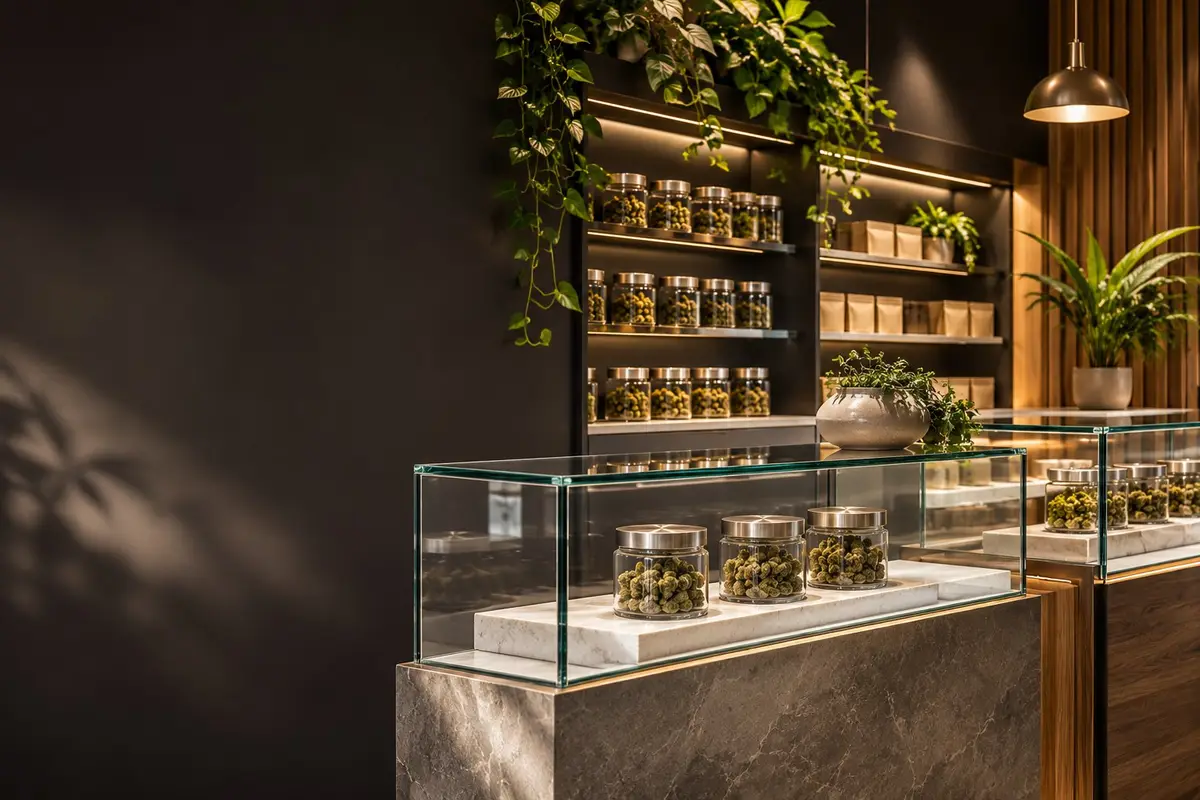
Cannabis Dispensary Accounting reconciled down to the drawer.
Dispensary accounting for licensed cannabis retailers who need POS sales, cash, excise, and inventory to agree every day, and a tax return built on the narrow cost of goods sold a reseller is allowed.
A dispensary runs on high transaction volume, heavy cash, and thin margins after tax. Your POS, your cash counts, your bank deposits, and your track-and-trace inventory all describe the same day, and when they disagree, the gap usually surfaces months later. Dispensary accounting at TreeStar starts with that daily reconciliation, then carries the results into excise and sales tax records, vendor balances, and a federal return built on the cost of goods sold a reseller can support. Because §280E leaves little room elsewhere, we focus our effort where accuracy changes the outcome.
Where it gets complicated
- 01 POS, cash, and bank
Discounts, voids, returns, and cash drops can push POS reports, drawer counts, and deposits apart. Small daily differences become large unexplained variances by year-end.
- 02 Excise held for the state
Retailers collect California cannabis excise tax from customers and remit it to CDTFA. Recording it as revenue, or remitting from the wrong period, distorts both your margins and your filings.
- 03 A reseller's narrow COGS
For a retailer, inventory cost generally covers the product price, net of discounts, plus the cost of getting it to your store. Sales-floor rent, budtender wages, and marketing generally fall outside it, so §280E reaches most of your overhead.
- 04 Shrink and adjustments
Theft, damaged product, expired goods, and count errors all reduce inventory. Each adjustment needs a reason, a matching state record, and a consistent entry in your books.
- 05 Vendor credits and promotions
Brand promotions, vendor credits, and returns change what you actually paid for product. If they are booked as other income or ignored, both COGS and vendor balances end up wrong.
How TreeStar helps
We match POS reports, cash counts, electronic payment settlements, and deposits on a regular cadence, so variances surface while the shift is still fresh.
→ accounts_payable Keep vendor balances trueWe record invoices, credits, and promotional allowances against each brand, so you pay the right amount and inventory reflects your real cost.
→ business_tax Build a defensible returnWe prepare your federal return with reseller COGS supported by purchase records, and your California return with the deductions the state allows.
→ compliance Keep store payroll compliantWe handle payroll filings and records for budtenders, managers, and security staff, with California requirements applied.
→What you can expect
Daily sales that tie to cash and deposits
Excise and sales tax records that match your filings
A reseller COGS figure backed by invoices
Common questions
Why is so little of our overhead deductible federally?
§280E denies ordinary deductions for trafficking in Schedule I substances, which includes adult-use retail sales. A retailer's cost of goods sold is generally limited to product cost and inbound charges, so most store expenses fall under the disallowance.
How should excise tax show up in our books?
Excise you collect is owed to the state, so it belongs in a liability account until it is remitted to CDTFA. We reconcile that account to your returns so each period's collections and payments match.
Can you help a dispensary with medical and adult-use sales?
Yes. State-licensed medical cannabis now sits in Schedule III, while adult-use remains Schedule I and subject to §280E, so we help you keep sales, inventory, and costs separated in a way that supports any allocation.
Need a referral?
We work alongside the attorneys, consultants, and other specialists your industry relies on. Tell us what you need and we will make an introduction.
Licensing, entity structure, contracts, and regulatory questions.
→ request_referral Metrc and track-and-trace specialistSetup, cleanup, and training so the system matches the shelf.
→ request_referral Compliance consultantStandard operating procedures, inspections, and state and local readiness.
→ request_referral Insurance brokerCoverage for product, property, crops, and liability in regulated markets.
→ request_referral Banking and payment solutionsInstitutions and processors that serve licensed operators.
→Highly Regulated Industries insights
Six what-if scenarios for regulated businesses, from a banned product to a lost processor: what breaks first, the warning signs, and the first moves.
→
Regulation is a variable, not a constant. How to model ranges, scenarios, triggers, and reserves for rules that keep moving.
→
Medical cannabis moved to Schedule III. Licensing, track-and-trace, testing, excise tax, banking, and state lines did not. What each layer still costs.
→