
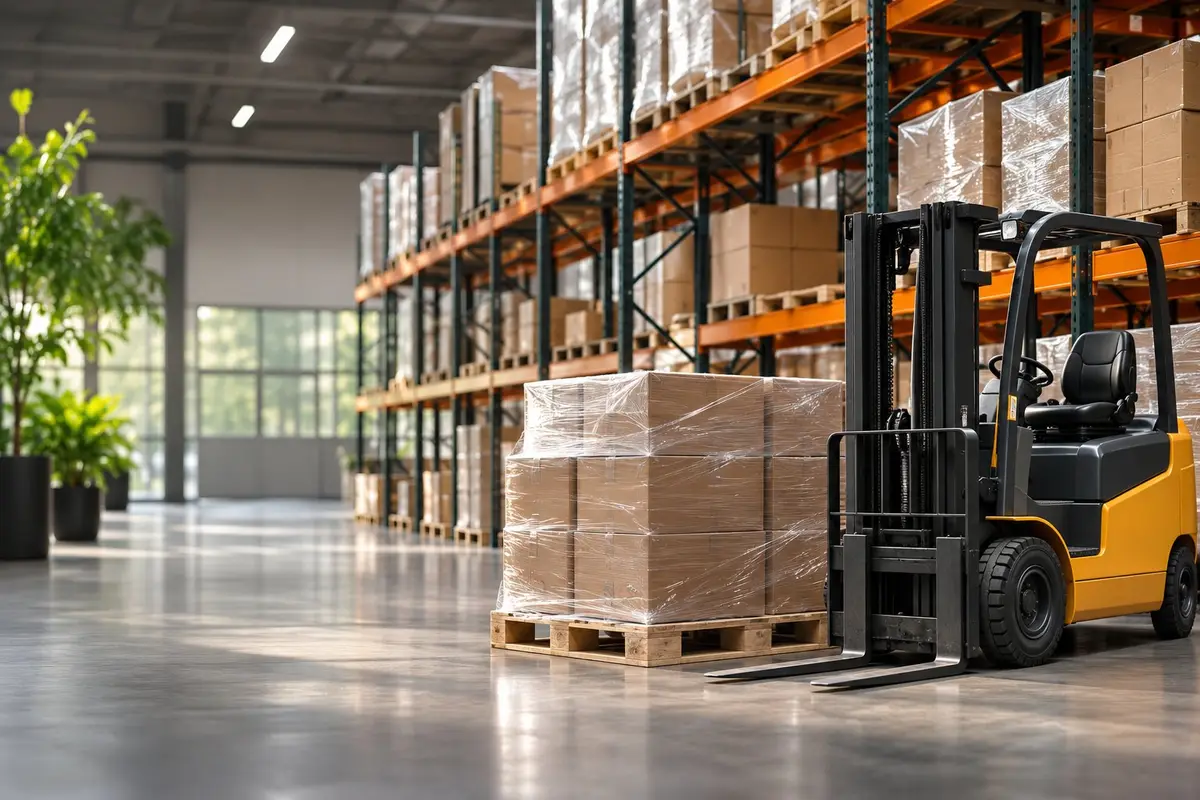
Cannabis Distribution Accounting where product changes hands.
Cannabis distribution accounting for licensed distributors who move, test, and wholesale product and need transfers, margins, and receivables that reconcile.
Distributors sit between every other license type. Product arrives from cultivators and manufacturers, waits on lab results, moves under manifests, and leaves on terms to retailers who may pay slowly. Cannabis distribution accounting has to follow ownership and custody at each handoff: what you own versus what you only transport, what is on hold pending test results, and what is in transit at month-end. TreeStar builds books that reflect those distinctions, reconciles them to your track-and-trace transfers, and gives you wholesale margin and receivables reporting you can manage from.
Where it gets complicated
- 01 Owned versus transported
Some product you buy and resell, and some you only move or hold for another licensee. Mixing the two inflates inventory and revenue and muddies your cost of goods sold.
- 02 Testing handoffs
In California, distributors arrange lab testing and quality assurance review before product reaches retail. Batches on hold, retests, and failed results all need a clear inventory status and cost treatment.
- 03 Inventory in transit
Product on a manifest at month-end belongs somewhere on your balance sheet. Cutoff errors between shipping and receiving distort both inventory and the period's margin.
- 04 Retailer receivables
Retail accounts often pay on extended terms, and some pay late or in part. Aging, credit limits, and steady follow-up decide whether wholesale volume turns into cash.
- 05 Thin wholesale margins
Freight, fuel, vehicle costs, and testing fees eat into each wholesale order. Knowing margin by brand, product, and account shows which relationships are worth growing.
How TreeStar helps
We track invoices by retail account, apply payments correctly, and keep an aging report you can act on before balances go stale.
→ bookkeeping_accounting Reconcile transfers to the booksWe match manifests and track-and-trace transfers to inventory each month, keeping owned product separate from product you only transport.
→ performance_kpi_analysis Report margin by accountWe measure wholesale margin after freight and testing costs by brand, product, and customer, so pricing and routing decisions rest on facts.
→ business_tax File returns that fit your roleWe prepare business returns with COGS built from the inventory you actually own, and California returns that reflect the state's separate treatment.
→What you can expect
Inventory that matches every manifest
Receivables you can see and collect
Margins measured by account and brand
Common questions
Should product we only transport be on our books?
Generally not as inventory, if you do not own it, though you still need records of what you hold and move. We set up tracking that keeps custody and ownership separate, so inventory and revenue reflect only your own product.
How do we account for failed lab tests?
Failed batches may be remediated, retested, or destroyed, and each path changes the inventory and cost picture. We record the status as it changes and keep the cost treatment consistent with your inventory method.
Does §280E apply to distributors?
For adult-use product you buy and resell, §280E generally applies, so cost of goods sold becomes the key figure. Medical activity may be treated differently now that state-licensed medical cannabis sits in Schedule III, so distributors handling both need records that separate them.
Need a referral?
We work alongside the attorneys, consultants, and other specialists your industry relies on. Tell us what you need and we will make an introduction.
Licensing, entity structure, contracts, and regulatory questions.
→ request_referral Metrc and track-and-trace specialistSetup, cleanup, and training so the system matches the shelf.
→ request_referral Compliance consultantStandard operating procedures, inspections, and state and local readiness.
→ request_referral Insurance brokerCoverage for product, property, crops, and liability in regulated markets.
→ request_referral Banking and payment solutionsInstitutions and processors that serve licensed operators.
→Highly Regulated Industries insights
Six what-if scenarios for regulated businesses, from a banned product to a lost processor: what breaks first, the warning signs, and the first moves.
→
Regulation is a variable, not a constant. How to model ranges, scenarios, triggers, and reserves for rules that keep moving.
→
Medical cannabis moved to Schedule III. Licensing, track-and-trace, testing, excise tax, banking, and state lines did not. What each layer still costs.
→